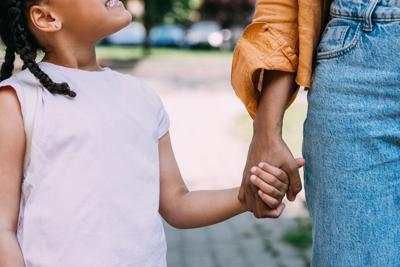

An unrecognizable woman holding hands with her anonymous baby girl as they walk down the street.
Sixty-seven percent of parents say raising children costs more than they expected — and the most telling part of that number is what's buried inside it. Thirty-eight percent don't just say it costs more. They say it costs much more than anticipated. These aren't families who walked into parenthood blindly. Many of them read the books, ran the spreadsheets, and still found themselves financially blindsided.
The usual suspects get most of the attention. Childcare and food dominate nearly every parenting budget guide written in the last decade, and for good reason — they're real and they're enormous. But the families who land in that 38% category aren't typically undone by the costs they saw coming. They're undone by the ones they didn't.
The Costs That Show Up Before You're Ready
According to Rocket Mortgage's research on the cost of raising a family, 24% of parents saw their monthly spending jump by $1,000 or more after having children. That kind of increase is hard to absorb even when you expect it. When it arrives attached to costs you didn't anticipate, it can feel like the floor has shifted.
People are also reading…
One of the first surprises is health insurance. Adding a dependent to an employer-sponsored plan increases the monthly premium in ways that rarely appear in early budget planning conversations. Depending on the plan tier, a family could be paying $200 to $500 more per month before a single pediatric copay is factored in. Most parents-to-be calculate baby gear. Very few calculate the benefits enrollment form they'll fill out in a hospital recovery room.
Pediatric dental coverage is another quiet shock. Many health insurance plans do not include pediatric dental or bundle it in ways that require a separate premium. The American Academy of Pediatrics recommends a child's first dental visit by age one, which means these costs arrive earlier than parents typically expect.
Clothing, Gear, and the Growth Cycle Nobody Budgets For
Infant clothing is purchased once and worn approximately four times before it no longer fits. This is not an exaggeration. In the first twelve months, many babies move through three to five clothing sizes. Parents who stock up on newborn and 0-3 month items — especially those who receive them as gifts — often find they own mountains of clothing their child outgrows before fully using.
The gear cycle compounds this. A rear-facing infant car seat typically has a weight limit that most children exceed between 9 and 12 months, which triggers the purchase of a convertible seat. That seat will eventually be replaced by a booster. Three car seats across childhood is not unusual, and each transition carries a $100 to $400 cost depending on safety ratings and features.
Strollers follow a similar arc. The travel system that works perfectly for a newborn becomes impractical once a toddler wants to walk half the time and be carried the other half. High chairs transition to booster seats. Baby monitors get upgraded. Baby gates are purchased, installed, and then may be removed and re-installed as the child gains access to new areas of the home. None of these items are luxuries. All of them have a shorter useful life than the purchase price suggests.
Social and Activity Costs That Sneak Up on Families
The birthday party economy is real and it arrives without much warning. Once a child enters preschool or kindergarten, the social calendar fills with invitations. A family with one child in a class of twenty can reasonably expect to attend fifteen to twenty birthday parties per year, each requiring a gift. At $20 to $30 per gift, that's $300 to $600 annually on other children's birthdays alone.
Hosting a party for your own child adds another layer. Venue fees, supplies, food, and favors for a modest gathering can easily reach $200 to $500 before any entertainment is added.
Extracurricular activities follow closely behind. By age four or five, children begin expressing interest in soccer, gymnastics, swimming, dance, or music lessons. Each of these programs carries registration fees, equipment costs, and uniform or recital costs that parents often don't encounter until they're already enrolled. A single season of recreational soccer can run $150 to $300 when cleats, shin guards, and the registration fee are combined.
School-age expenses also begin earlier than many parents expect. Activity fees, school supply lists, and field trip costs start in kindergarten, and in some districts they accumulate quickly. A single school year can generate $200 or more in small, incremental school-related costs that never appear in a single budget line.
Convenience Spending: The Invisible Cost of Exhaustion
Sleep deprivation doesn't appear in any parenting cost calculator, but its financial effects are measurable. In the first year especially, exhausted parents make spending decisions that they wouldn't make otherwise. Takeout and food delivery replace home-cooked meals more frequently. Grocery delivery services get added because managing a baby in a supermarket is genuinely difficult. Subscription boxes and apps get purchased for developmental stimulation or parental sanity and then forgotten.
These aren't failures of willpower. They're predictable responses to an unpredictable new demand on a parent's time and cognitive bandwidth. But they add up. A family spending an extra $15 on delivery fees four nights a week is looking at roughly $250 per month before the food cost is counted.
The survey data reflects how heavy this weight becomes over time: 46% of parents say child-related finances cause them stress always or usually. More than half — 58% — have gone into debt through credit cards or loans for child-related expenses. Fifty percent have delayed or avoided having additional children specifically because of financial concerns.
These numbers don't point to poor planning. They point to a gap between what parenting cost guides prepare families for and what parenting actually costs. Budgeting for the visible categories is a reasonable starting point. But the families who fare best are usually the ones who left room in their plan for the costs no one mentioned.